Securing a mortgage, business loan, or automobile financing is among the most consequential financial decisions an individual or enterprise undertakes. Yet, the underlying mathematics of Equated Monthly Installments (EMIs) often remains opaque, leaving borrowers vulnerable to predatory fee structures.
The Mathematical Mechanics of Reducing Balance Interest
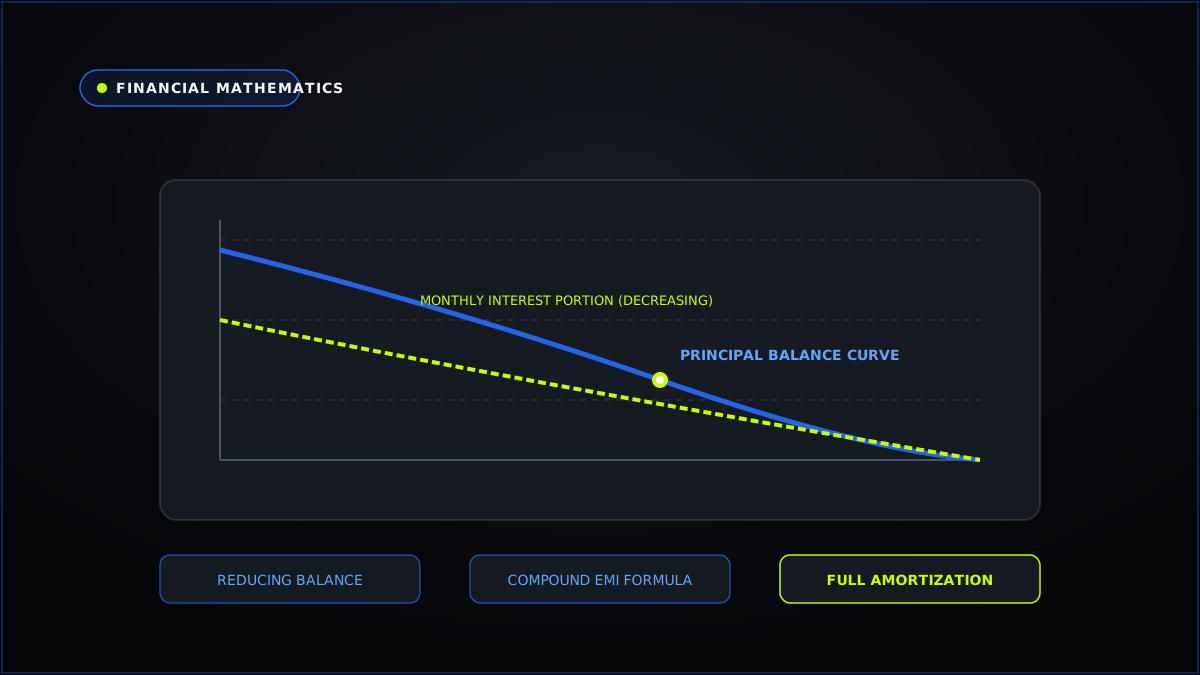
Unlike simple interest calculations where the principal remains fixed, standard consumer loans utilize the reducing balance methodology. In the early years of a 20-year or 30-year amortization schedule, over 70% of each monthly installment is absorbed strictly by interest charges, with only a negligible fraction retiring the underlying principal debt.
By understanding how amortization tables front-load interest, borrowers can strategically time unscheduled principal prepayments to dramatically compress the loan tenure and save tens of thousands of dollars in cumulative interest.
Strategic Principal Prepayment: The Accelerated Payoff Formula
Making a single additional monthly installment each calendar year, or bumping monthly payments by a modest 10%, directly chips away at the principal balance before interest compounds. For a $300,000 mortgage at 6.5% interest, an extra $200 per month reduces the payoff duration by nearly 5 full years and prevents more than $60,000 in interest accumulation.
Step-by-Step EMI Computation and Verification
Before meeting loan officers or signing commercial promissory agreements, simulate your exact loan schedule using the Commeronix Loan EMI Calculator. You can adjust the principal, interest rate, and tenure while instantly generating a visual breakdown of total interest versus principal payout.
Use the free Commeronix tool for this workflow:
Try the Loan EMI Calculator client-side with 100% privacy and zero latency.